OCIP Insurance
Wrap-Up Placement
Price my project

The firm

Cary W. White

Managing Director at ISU Insurance Services of San Francisco. Thirty-eight years in construction insurance, ten of them underwriting on the carrier side and twenty-eight placing programs for owners, developers and general contractors.

In one paragraph

Who you would be dealing with

Cary W. White has spent 38 years in construction insurance. The first ten were on the carrier side, underwriting builders risk and complex property exposures. The twenty-eight since have been in retail brokerage, on wrap-ups, project-specific and annual programs for residential developers, general contractors and other construction clients.

He is also one of the original authors of the project liability application that much of the industry still uses to submit wrap-ups to carriers.

California license #0B77854, at ISU Insurance Services of San Francisco, California license #0778092. He answers his own phone at 415-613-5589.

What we place, and where
Programs
Owner-controlled (OCIP) and contractor-controlled (CCIP) wrap-ups, rolling wrap-ups, builders risk, and project-specific or practice liability where a wrap is not the right structure.
Project types
Multifamily and mixed-use, condominium and for-sale residential, podium and wood-frame, commercial, tenant improvement, and industrial.
Where
Licensed in all 50 states. Deepest bench in California, where the wrap-up statutes are covered in detail on this site.
Project size
No minimum to ask. A wrap typically starts to pay for itself around $25 million in hard construction value. Smaller projects are placed on conventional structures instead.
Who we work with
Owners, developers, general contractors, and subcontractors buying practice coverage for the off-site gap.
Who you deal with
Cary W. White, producer. ISU Insurance Services of San Francisco, CA Lic. #0778092. Cary W. White, CA Lic. #0B77854. We place coverage; we are not the carrier.

The work

What he places

Cary W. White is Managing Director at ISU Insurance Services of San Francisco and handles the wrap-up placements there. Thirty-eight years in construction insurance, split unevenly between two sides of the same business.

The first ten were on the carrier side, underwriting builders risk and complex property exposures. That is where you learn what an underwriter is actually worried about, which turns out to be a different question from what the application asks. The twenty-eight since have been in retail brokerage, advising residential developers, general contractors and other construction clients on project-specific and annual programs.

He is also one of the original authors of the project liability application that much of the industry still uses to submit wrap-ups to carriers. In practice that means he knows what each question is actually asking for, and where a thin answer will cost you at quote.
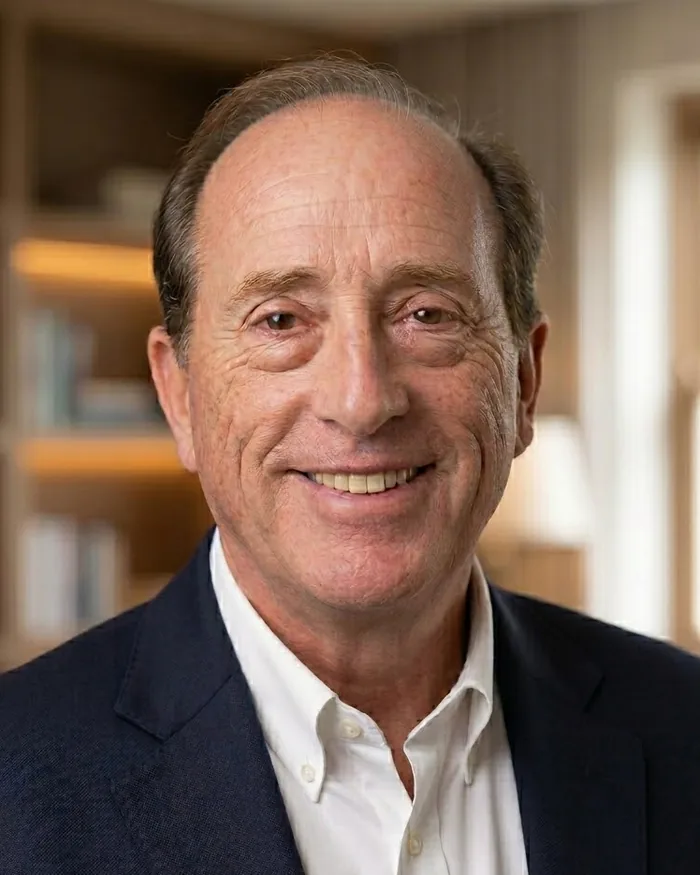
Cary W. White

Managing Director · ISU Insurance Services of San Francisco

Owner-controlled and contractor-controlled wrap-ups, rolling programs, builders risk, and project-specific and practice liability where a wrap is not the right structure. Owners, developers, general contractors, and subcontractors buying practice coverage for the off-site gap.

cwhite@isusf.com
415-613-5589
California license #0B77854

He is licensed in all 50 states through ISU Insurance Services of San Francisco. In practice the deepest bench is California, where the wrap-up statutes are their own body of law and where most of the residential wrap work in his book sits. Projects outside California get placed too, and where a local relationship serves the client better, the ISU network makes that straightforward.

How he works

Structure first, market second

The question most people arrive with is whether their project should have an OCIP. That is usually the wrong first question. The better one is what insurance structure gives this particular project the most reliable protection, the clearest allocation of responsibility, and the fewest gaps when a serious claim arrives.

Sometimes the answer is a wrap-up. Sometimes it is a project-specific liability policy over the owner and the general contractor, with the trades keeping their own insurance. Sometimes conventional contractor insurance with properly written requirements is entirely appropriate. ISU places all of them, which means there is no structure the recommendation needs to land on.

Two things follow from working that way. The first is that a meaningful number of projects that come in asking about a wrap leave with something else, and that is a normal outcome rather than a failed one. The second is that the structure conversation has to happen before the bid package goes out, because bid credits, enrollment and the disclosure that California requires all have to be set up before trades are bought.

On project size

A wrap typically starts to pay for itself somewhere around twenty-five million dollars in hard construction value. That is a rule of thumb, not a filter. Smaller projects get priced, and most of them get placed on a conventional structure instead. There is no minimum to ask.

Writing

What he writes about

Most of the material on this site started as something Cary wrote for clients or for the trade. The recurring subjects:

The practical versions of several of these are on this site already: the program design library covers term, covered locations, multiple projects and exclusions, and the California rules page covers the statutory layer.

The firm

ISU Insurance Services of San Francisco

ISU Insurance Services of San Francisco is an independent retail brokerage, California license #0778092, and part of the ISU network of independently owned agencies. Retail matters here for a practical reason. A retail brokerage can place the conventional structure as readily as the wrap, so a project that does not suit a wrap-up does not have to go somewhere else to get insured.

ISU places coverage with insurance carriers on behalf of its clients. It is not an insurance carrier. It does not issue policies, underwrite risk or make coverage determinations, and nothing on this site is an offer of insurance, a quote or a binder.

Getting started

What a first conversation looks like

Fastest route is the form at the bottom of this page, which goes straight to Cary. Email and phone work equally well.

What helps on the first pass, in rough order of usefulness:

  1. What is being built, where, and the hard construction value.
  2. Tenure. For-sale, rental, owner-occupied, or build to suit.
  3. Schedule. Start date and duration, and whether the duration is realistic.
  4. Who would sponsor the program, and whether that entity will still exist in ten years.
  5. Roughly how many trades, and an estimate of construction payroll if you have one.
  6. Any loss history on comparable projects, and anything that changed afterwards.
  7. Whether anything is already in place, and whether bids have gone out.

None of that has to be complete. A project name, a state and a value is enough to get a useful answer about whether a wrap is even the right conversation. The detail matters when it comes time to market the program to underwriters, and a well assembled submission gets a materially better answer than the same project sent over as a contract value and a start date.

Questions

Common questions

Where is Cary White licensed?

California license #0B77854, and licensed in all 50 states through ISU Insurance Services of San Francisco, California license #0778092. Most of the wrap-up work in the book is California, particularly residential, where the state has its own statutory layer.

Can he place a wrap-up outside California?

Yes. Licensing covers all 50 states. California is where the deepest experience sits, and on a project in a state where a local relationship would serve the client better, the ISU network of independently owned agencies makes a referral straightforward.

What does he place besides wrap-ups?

Project-specific and practice liability, builders risk, and conventional contractor programs. ISU is a retail brokerage, so a project that is not suited to a wrap can be placed on another structure without going elsewhere.

Is there a minimum project size?

No minimum to ask. A wrap-up typically starts to pay for itself around twenty-five million dollars in hard construction value, and projects below that are quoted and usually placed on a conventional structure instead.

Who do I actually deal with?

Cary W. White directly. He answers his own phone at 415-613-5589 and reads his own email at cwhite@isusf.com, and the form on this site goes to him.

Does ISU issue the policy?

No. ISU Insurance Services of San Francisco is a licensed insurance brokerage. It places coverage with insurance carriers on behalf of clients. It is not a carrier, does not issue policies, does not underwrite risk and does not make coverage determinations.

Next

Where to go from here

If you came here to work out whether your project should be on a wrap, these are the places to start.

Pricing

Price your project

Tell us about the project and we will give you a straight answer on whether a wrap makes sense for it. If it does not, we will say so, and then we will price the structure that does. That answer is worth more to you than a placement that costs more than it saves. There is no project minimum to ask. This goes straight to Cary White, who handles wrap-up placements for our construction clients.

The project
Structure and exposure
You

We will come back with a price range and what else underwriters will need. No obligation, and we will tell you if a wrap is the wrong answer.