OCIP Insurance
Wrap-Up Placement
Price my project

Program design

Policy term and the tail

A wrap-up has two clocks. One runs while the job is being built. The other starts when the job is finished and runs for years, and it is the one that costs the money.

One of four program design decisions.

The short version

Two clocks

The construction term covers bodily injury and property damage arising out of work at the site while the project is being built. It is normally written to the scheduled completion date plus some margin.

The completed operations extension covers claims that arise after the work is finished, which on a defect claim is where almost all of them arrive. It is bought up front, for a fixed number of years, and it cannot be bought back later once the program has closed.

Getting the term wrong is the most common and the most expensive design mistake in a wrap.

What we place, and where
Programs
Owner-controlled (OCIP) and contractor-controlled (CCIP) wrap-ups, rolling wrap-ups, builders risk, and project-specific or practice liability where a wrap is not the right structure.
Project types
Multifamily and mixed-use, condominium and for-sale residential, podium and wood-frame, commercial, tenant improvement, and industrial.
Where
Licensed in all 50 states. Deepest bench in California, where the wrap-up statutes are covered in detail on this site.
Project size
No minimum to ask. A wrap typically starts to pay for itself around $25 million in hard construction value. Smaller projects are placed on conventional structures instead.
Who we work with
Owners, developers, general contractors, and subcontractors buying practice coverage for the off-site gap.
Who you deal with
Cary W. White, producer. ISU Insurance Services of San Francisco, CA Lic. #0778092. Cary W. White, CA Lic. #0B77854. We place coverage; we are not the carrier.

Clock one

The construction term

The construction term is the period during which the program covers work in progress at the site. It normally runs from the start of operations to the scheduled completion date, with some margin built in.

The margin is the part worth negotiating. Construction schedules slip. A program written exactly to a scheduled completion date that then slips by five months leaves a gap, or forces an extension to be bought under time pressure at whatever the underwriter decides it is worth at that point.

Before binding, three questions should have answers in writing:

None of these is unusual. They are routine terms that frequently go unasked because the conversation at binding is about premium.

Clock two

The completed operations tail

The second clock starts when the work is finished. The completed operations extension covers claims arising out of the completed work, and on most construction risks that is where nearly all the serious claims come from.

Nothing much goes wrong during construction. A roof that was flashed badly in 2026 does not announce itself in 2026. It announces itself in 2032, when water has been getting into the wall for four years and an owners association has commissioned a report.

Two properties of the tail make it the single most important number in a wrap-up proposal.

It is bought once. The extension is purchased when the program is placed, for a stated number of years. Once the program has closed there is no mechanism for buying more years. A sponsor who bought five years and needed ten does not discover the problem until year six, and at that point there is nothing to do about it.

It is most of the premium. On residential work in particular, the construction period portion is comparatively cheap and the tail is what the money is actually buying. A proposal that undercuts another on premium is very often just selling fewer years.

Setting the number

How many years

The right length is the one that covers the period during which a claim can still be brought in the state where the project is, for the type of work being done. That is a legal question before it is an insurance question, and it is worth getting counsel to answer it rather than copying the term from the last deal.

California is the most commonly asked about. There, an action for a latent construction deficiency can be brought for ten years from substantial completion under Code of Civil Procedure section 337.15, with a shorter period for patent deficiencies. The Right to Repair Act in Title 7 of the Civil Code adds functionality standards and a pre-litigation process with its own component-by-component time limits. In practice that produces ten-year tails on California for-sale residential as the normal answer.

Other states run shorter, and commercial work often sits comfortably at a shorter term than residential in the same state, because the claim pattern is different. A distribution center does not generate an association defect action.

The question to ask

Not "how long is standard?" but "how long can somebody still sue over this work in this state, and does the term cover that?" Those two questions have different answers more often than they should.

Mechanics

Things that quietly shorten the tail

A stated ten-year extension does not always deliver ten usable years. Four things to check in the wording.

  1. When it starts. Substantial completion, final completion, certificate of occupancy, or the end of the construction term. On a phased project these can be a year or more apart, and on a multi-building project the question is whether the clock starts per building or at the end of the last one.
  2. Whether the aggregate reinstates. A single aggregate limit covering the whole completed operations period is a different product from one that reinstates annually. On a ten-year tail with a single aggregate, the first serious claim can leave very little for the rest of the decade.
  3. Whether the sponsor has to do anything. Some structures require notice, reporting or a payment to keep the extension in force. If so, somebody has to still be watching for it eight years after the project team has moved on.
  4. Who the named insured will be. A single purpose entity that dissolves after sell-out may not exist when the claim arrives. That is solvable at placement and difficult afterwards.

On a phased or rolling program the term question gets more complicated again, because each project has its own completion date and therefore its own clock. The multiple projects page covers that.

Questions

Common questions

Can completed operations coverage be added after the program closes?

Generally no. The extension is bought when the program is placed, for a stated number of years. That is why the term is the design decision with the least room for correction later.

How long should the tail be in California?

Ten years is the normal answer on for-sale residential, because Code of Civil Procedure 337.15 allows an action for a latent construction deficiency for ten years from substantial completion. Commercial work in the same state often sits at a shorter term because the claim pattern is different. It is worth having counsel confirm the applicable period for the specific work.

What happens if the project runs longer than the policy term?

The construction term has to be extended. Whether that is automatic, negotiated or subject to fresh underwriting, and at what price, should be settled at binding rather than discovered when the job is four months late. An agreed extension rate fixed at binding costs very little to ask for.

Does extending construction also extend the completed operations period?

Not automatically. Some structures start the completed operations clock from actual completion and some from the original scheduled date. It is worth confirming which, because a long delay can otherwise shorten the effective tail by the length of the overrun.

Does the aggregate limit reinstate during the tail?

It depends on the program. A single aggregate across the whole completed operations period means the first serious claim can leave very little for the remaining years. An annually reinstating aggregate costs more and behaves very differently. It is one of the questions worth asking before comparing two proposals on premium.

When does the tail start on a multi-building project?

It depends on the wording, and the two common answers are far apart. Per building, each one starts its own clock at its own completion. At the end of the project, every building gets the same start date, which is later and therefore longer for the buildings finished first. Check which one the proposal uses.

Next

Where to go from here

The other three design decisions.

Who you would be working with

Cary W. White
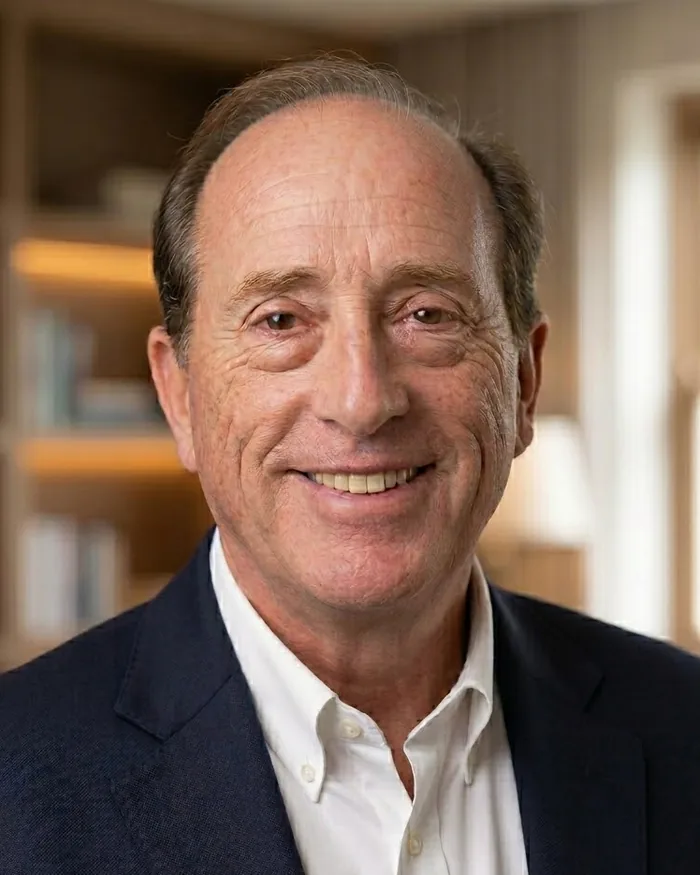
Cary W. White, Managing Director, ISU Insurance Services of San Francisco

Managing Director · ISU Insurance Services of San Francisco

Cary handles the wrap-up placements here. He has spent 38 years in construction insurance. The first ten were on the carrier side, underwriting builders’ risk and complex property exposures. The 28 since have been in retail brokerage, advising residential developers, general contractors and other construction clients on project-specific and annual programs.

He is also one of the original authors of the project liability application that much of the industry still uses to submit wrap-ups to carriers. In practice that means he knows what each question is actually asking for, and where a thin answer will cost you at quote.

cwhite@isusf.com · 415-613-5589

Pricing

Price your project

Tell us about the project and we will give you a straight answer on whether a wrap makes sense for it. If it does not, we will say so, and then we will price the structure that does. That answer is worth more to you than a placement that costs more than it saves. There is no project minimum to ask. This goes straight to Cary White, who handles wrap-up placements for our construction clients.

The project
Structure and exposure
You

We will come back with a price range and what else underwriters will need. No obligation, and we will tell you if a wrap is the wrong answer.